The fire is out, but the financial damage may only be starting. When the insurance offer arrives and the number feels wrong, you are not stuck. A fire damage claim lawyer can review your policy, challenge a low valuation, and fight for what you need to rebuild your life. At Godbey Giardina Law Group, we help families and business owners push back when insurers undervalue their losses. In this guide, we explain why settlements fall short and what you can do about it.
Why Insurance Companies Often Pay Less Than You Need
Insurance adjusters work for the insurer, and part of their job is controlling claim costs. Their first offer often arrives when you are displaced, exhausted, and in urgent need of money for hotels, clothing, and food. That timing matters. Adjusters may estimate repairs using low-cost materials and labor rates that do not match what local contractors actually charge. They may also rely on quick walkthroughs that miss damage hidden behind walls and above ceilings.
Many homeowners assume the first number is a fair assessment of their loss, but it is often just an opening position in a negotiation. Understanding that the offer is a starting point, not a final verdict, is the first step toward recovering what your policy promises. It is also why many people turn to a fire damage claim lawyer early.
Common Ways Fire Claims Get Undervalued
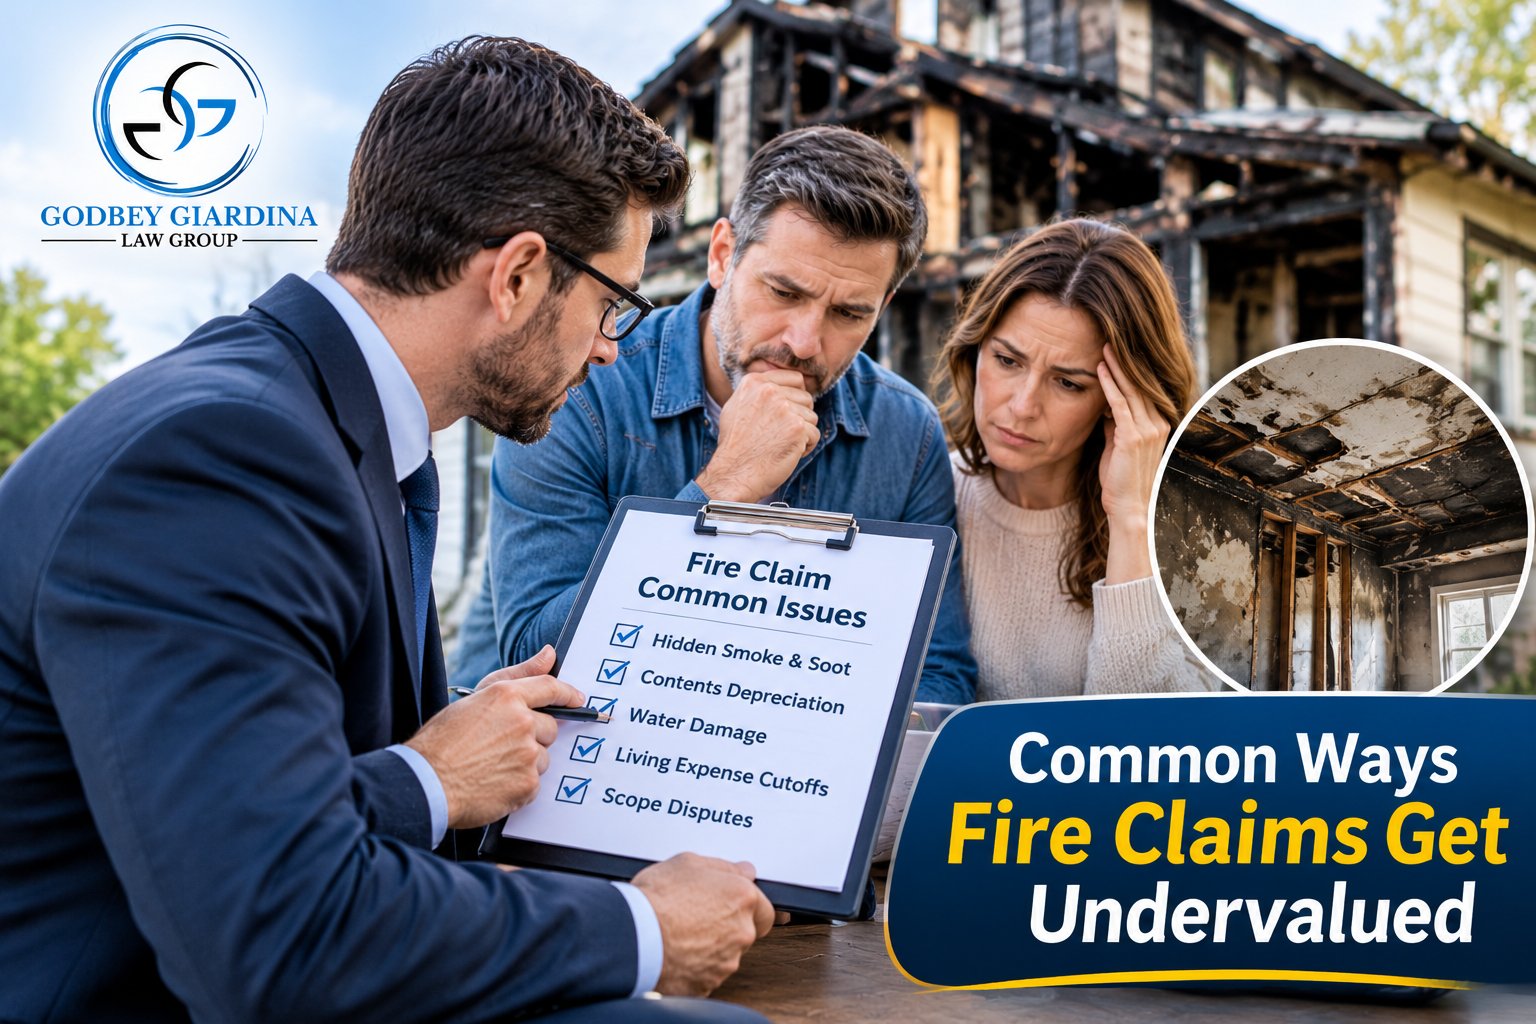
Underpayment rarely comes from one big error. It usually comes from several smaller ones that add up, and Fire and Smoke Damage claims are especially vulnerable because so much of the harm is hard to see. Watch for these problems:
- Hidden smoke and soot: Residue in HVAC systems, insulation, and wall cavities can affect air quality and leave lingering odors.
- Contents depreciation: Insurers may pay actual cash value instead of replacement cost, applying heavy depreciation to your belongings.
- Water damage from firefighting: This is often overlooked or classified separately.
- Living expense cutoffs: Hotel or rental coverage may end before repairs are finished.
- Scope disputes: The insurer calls the property repairable when it is really a partial or total loss.
Imagine receiving a $42,000 offer while three contractor estimates come in near $78,000. A fire damage claim lawyer is trained to close exactly that kind of gap.
What to Do Before You Accept Any Offer
Do not rush to sign. Accepting a settlement and signing a release can close the door on further recovery.
Start by asking the insurer for a detailed, line-by-line explanation of how it reached its number. Next, get independent estimates from licensed contractors and, when needed, restoration or industrial hygiene professionals who can document what the adjuster missed.
Keep photos, videos, receipts, repair estimates, and an inventory of lost belongings, along with every written communication with the insurer. Then read your policy closely, paying attention to coverage limits, replacement cost versus actual cash value, additional living expense terms, and deadlines.
Proof-of-loss requirements and filing windows can expire quietly, so track every date. Speaking with a fire damage claim lawyer before you sign anything can help you avoid costly mistakes. For general consumer guidance on insurance claims, the Insurance Information Institute is a helpful starting point.
Signs Your Insurer May Be Acting in Bad Faith
Insurers owe you a duty to handle your claim honestly and promptly. When they fall short, it may amount to bad faith. Warning signs include unreasonable delays, repeated requests for the same paperwork, failure to investigate the loss properly, misrepresenting what your policy covers, and denying a claim without a clear explanation.
Another red flag is an offer far below credible estimates with no justification. Not every slow response is bad faith, but a pattern should raise concern. Rules vary by state, and resources from the National Association of Insurance Commissioners can help you understand your rights as a policyholder. If you notice these behaviors, write down the dates, names, and details of each interaction. That record can become valuable evidence later.
When It’s Time to Hire a Fire Damage Claim Lawyer
You do not have to wait until the situation feels hopeless. Consider calling a fire damage claim lawyer if your offer is far below your contractors’ estimates, your claim has been delayed or denied, your living expense coverage is ending too soon, or you are being pressured to sign a release. Early involvement also helps protect deadlines and preserve evidence while it is still fresh.
Many people ask whether a public adjuster is enough. Adjusters can help with valuation, but they generally cannot file a lawsuit or pursue bad faith remedies on your behalf. When negotiations stall, legal action may be the only way to move an insurer. Many attorneys handle these cases on a contingency basis, so ask about fees during your first consultation.
How a Fire Damage Claim Attorney Changes the Outcome
A fire damage claim attorney levels the playing field. At Godbey Giardina Law Group, we analyze your policy to identify coverage that may have been overlooked, then build your case with expert-backed evidence that challenges the insurer’s valuation. We handle communication with the insurance company so you are not pressured into quick decisions, and we negotiate for the full value of your claim, including structural repairs, belongings, and living expenses.
If the insurer still refuses to act fairly, we are prepared to pursue litigation. We cannot promise a specific result, because every claim is different, but we can promise to explain your options clearly and advocate for a fair outcome. This article is general information, not legal advice.
Conclusion: Don’t Settle for Less Than You’ve Lost
A fire changes everything, but your settlement should not make recovery harder. If your insurance company’s offer does not cover what you have lost, you do not have to accept it. Our team at Godbey Giardina Law Group is ready to review your claim, explain your rights, and map out the next steps. You have already been through enough, and you should not have to fight the insurer alone.
Contact us today to schedule a consultation, and let us help you pursue the compensation you deserve. Don’t let a low offer decide your future. Speak with a trusted fire damage claim lawyer and take the first step toward a full recovery.
Frequently Asked Questions
Can I dispute my insurance company’s fire damage settlement?
Yes. You are not required to accept the first offer. You can ask for a line-by-line breakdown of how the insurer reached its number, submit independent contractor estimates, and provide documentation of any damage the adjuster missed. If the insurer still undervalues your claim, a fire damage claim lawyer can negotiate on your behalf or pursue further legal action.
How long do I have to file or dispute a fire damage claim?
It depends on your policy and your state. Policies often set deadlines for reporting a loss, submitting a proof of loss, and filing a lawsuit, and some are as short as one year. Because these windows can expire quietly, review your policy right away and speak with an attorney early to protect your rights.
What if my insurer denies my fire claim?
A denial is not always the end. Start by requesting the denial in writing, along with the specific policy language the insurer relied on. Then review it for errors, such as a misread exclusion or an incomplete investigation. You can appeal, file a complaint with your state’s insurance department, or work with a lawyer to challenge the denial and look into possible bad faith.
Does smoke damage count as fire damage?
In most cases, yes. Standard homeowners policies typically cover smoke and soot damage that results from a covered fire, including residue in walls, insulation, and HVAC systems. However, insurers often undervalue it because it is hard to see, so independent testing and thorough documentation are important.
Should I hire a public adjuster or a lawyer?
It depends on your situation. A public adjuster can help document and value your loss, and may be enough for a straightforward claim. If your claim has been denied, delayed, or lowballed, or you suspect bad faith, a lawyer is the better choice because only an attorney can file a lawsuit and pursue legal remedies for you.