Skip to content

Business Interruption Lawyer in Plantation, FL

 Serving Louisiana, Florida & Colorado 

Talk to a Business Interruption Attorney Today

Sales Promotion Presentation (1)

Results That Speak for Themselves

200
+
5 Star Reviews
2
k+
Clients Helped
$
100
M+
In Settlements
50
+
Years of Combined Experience
4
Office Locations Across 3 States
30
+
Team Members to Assist

Business Interruption Lawyer in Plantation, FL

A hurricane, fire, burst pipe, or other covered event can interrupt a Plantation business's operations and create significant lost income and additional expenses. Business interruption coverage may help address certain losses when the policy's requirements are met, but disputes can arise over coverage, the amount of the loss, and the period of interruption.

A business interruption lawyer can review the policy, documentation, and circumstances of the loss to help determine what coverage may apply and discuss available legal options. Godbey Giardina Law Group represents Plantation and Broward County businesses on a contingency fee basis, meaning no upfront attorney's fee is charged, and the attorney's fee is contingent on recovery.

Our office sits at 8751 W Broward Blvd, right in Plantation, and our attorneys have handled business interruption disputes for companies along Peters Road, W Sunrise Boulevard, and throughout the Gateway District. Here's what business interruption coverage actually requires, how Florida law affects a dispute, and how our team builds your case.

Godbey Giardina Law Group

What Business Interruption Insurance Covers and Common Coverage Disputes

Business interruption coverage may pay for lost income and certain ongoing expenses when a covered peril causes an interruption to your business. Depending on the policy, coverage may be subject to a waiting period, a defined period of restoration, policy limits, and other conditions.

Coverage depends on the specific language of your policy. Many commercial property policies require direct physical loss or damage caused by a covered peril before business income coverage applies. Whether a particular loss satisfies those requirements depends on the policy language, the cause of the loss, and the facts surrounding the interruption.

Depending on the policy, the dispute may involve coverage limits, waiting periods, exclusions, notice requirements, proof of loss, the period of restoration, or how business income and extra expenses are calculated.

A property damage claim may arise alongside a business interruption claim when the same event causes both physical damage and lost business income. The available coverage depends on the applicable policy provisions and the circumstances of the loss. 
Business Interruption Lawyer 1

Insurers may dispute a business interruption claim for several reasons, including:

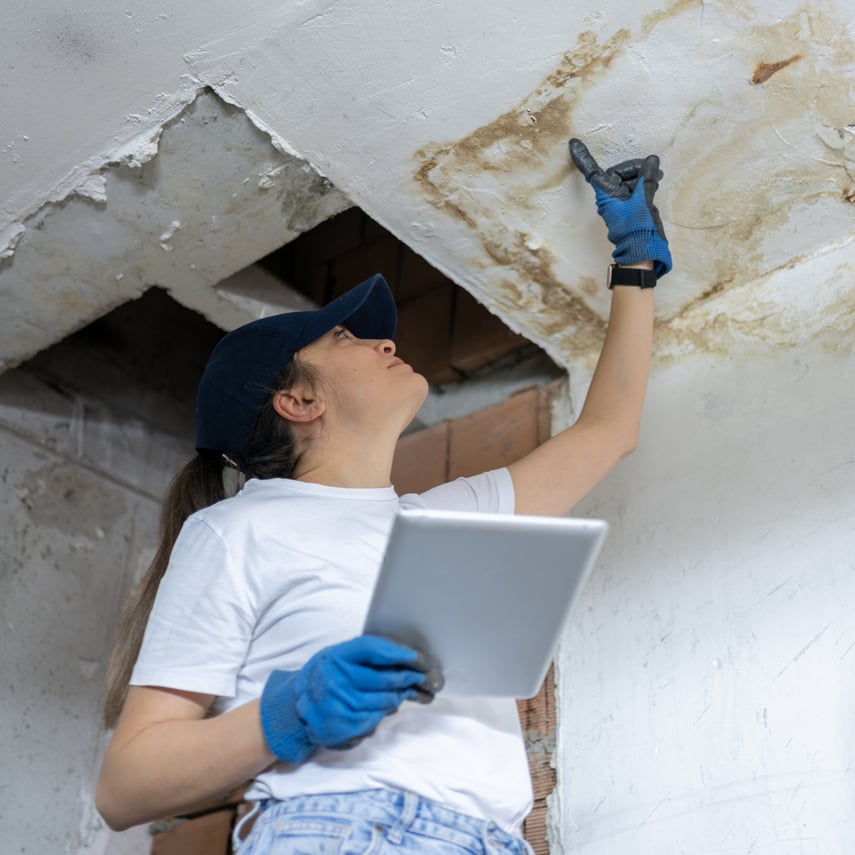
  • Disputing the extent of physical damage. Arguing that the documented damage does not satisfy the policy's coverage requirements.
  • Challenging the lost-income calculation. Disputing the amount of income or expenses claimed.
  • Disputing the restoration period. Arguing that the business could have resumed operations sooner.
  • Applying policy exclusions or conditions. Pointing to exclusions, limitations, reporting requirements, or other policy provisions.

Strong documentation can help establish the extent and circumstances of a business interruption loss.

  • Dated photos and video of the damage, taken before cleanup begins.
  • Two to three years of financial records: P&L statements, tax returns, and bank statements.
  • A daily closure log tracking how long the business was affected and why.
  • Receipts for temporary repairs and other extra expenses.

Godbey Giardina Law Group

Florida's Rules for Business Insurance Disputes

Florida law puts specific procedural requirements on a business owner disputing a denied or underpaid claim, and missing one can cost you the case.

Florida's civil remedy process can also become important in insurance disputes. Under Fla. Stat. §624.155, an insured seeking to pursue a statutory bad-faith remedy generally must provide a Civil Remedy Notice to the insurer through the Department of Financial Services. The statute provides a 60-day period for the insurer to pay damages or correct the circumstances identified in the notice.

For certain first-party property-insurance bad-faith claims, §624.1551 additionally requires the insured to establish through an adverse adjudication that the insurer breached the insurance contract and obtain a final judgment or decree. An appraisal award by itself does not satisfy that requirement.

Timing matters just as much as the coverage dispute itself. Our blog on what Florida claim denials often come down to walks through a real case where delayed reporting and unmitigated damage cost a policyholder part of their claim. The same lessons apply directly to business interruption disputes.

Business Interruption Lawyer 2

Godbey Giardina Law Group

Why Business Interruption Claims Get Denied, Delayed, or Underpaid

Most denials and lowball offers trace back to a handful of recurring disputes:

  • The "direct physical loss" trigger. Coverage disputes may arise over whether the loss satisfies the policy's requirement for direct physical loss or damage, particularly when a business interruption results from contamination, supply-chain disruption, or a civil authority order.
  • Broad policy exclusions. Policy exclusions may also affect whether a particular business interruption loss is covered. The applicable exclusions depend on the policy and circumstances of the loss.
  • Disputes over the period of restoration. An insurer may argue a business should have reopened faster than it did, cutting the payout short.
  • Thin documentation. A business income loss claim built on rough estimates instead of real financial records gives an adjuster an easy reason to underpay a claim

This is also where a bad faith insurance dispute can surface, when an insurer denies, delays, or underpays a claim without a reasonable basis for doing so. Depending on the state and circumstances, an insurer's unreasonable denial, delay, or handling of a covered claim may raise issues involving statutory or common-law insurance duties.

Business Interruption Lawyer 3

Godbey Giardina Law Group

Why Plantation Businesses Turn to Godbey Giardina Law Group

Business interruption claims are part of our broader business loss and interruption practice, which our Florida office in Plantation handles for businesses throughout Fort Lauderdale, Sunrise, and the rest of Broward County.

  • More than $100 million recovered for our clients.
  • 2,000+ clients represented.
  • 200+ five-star reviews.
  • 50+ years of combined legal experience.

Our attorneys handle a business interruption dispute the same way regardless of the size of the claim:

  1. Free policy review to see what your coverage actually says.
  2. Documentation of your lost income, expenses, and closure timeline.
  3. Negotiation with the insurance company on your behalf.
  4. Litigation, if a fair settlement doesn't come together.

No attorney can guarantee a specific outcome before reviewing your policy and your records, but a full, individualized review costs you nothing upfront.

We work on a contingency fee basis: no upfront costs, and no fee unless we recover money for you. Every claim is decided on its own policy language and documentation, and past results don't guarantee a similar outcome in yours.

Business Interruption Lawyer 4

What Plantation Business Owners Ask About Business Interruption Claims

These are the questions we hear most often from business owners throughout Plantation and Broward County.

A business interruption lawyer reviews your policy, documents your lost income and expenses, and negotiates or litigates against the insurance company on your behalf. The goal is to evaluate the coverage available under the policy and pursue amounts that may be supported by the policy and the documented loss.

It covers lost income and ongoing expenses when a covered peril causes direct physical loss that forces your business to close or slow down. The duration of coverage depends on the policy's period of restoration, limits, extensions, and other applicable terms.

Yes. Our Florida attorneys are licensed to practice in Florida and represent clients in insurance disputes throughout Broward County. We regularly handle Civil Remedy Notice filings and litigation tied to sections 624.155 and 624.1551 of Florida's insurance code.

A denial does not necessarily end your ability to challenge the insurer's position. An attorney can review the denial letter, policy language, and supporting documentation to evaluate potential coverage and legal options.

Our office is at 8751 W Broward Blvd Suite 408, Plantation, FL 33324. We also represent businesses throughout Fort Lauderdale, Sunrise, and greater Broward County, and initial consultations are free.

We work on a contingency fee basis, so there's no upfront cost to hire us. You pay no attorney's fees unless we recover money for you, and your initial case review costs nothing either way.

The applicable deadline depends on the type of claim, the insurance policy, the date of loss, and the legal theory involved. Florida law provides specific limitations periods for certain insurance-contract actions, while policy provisions may also impose notice and proof-of-loss requirements. Because missing an applicable deadline can affect your rights, have a denied or underpaid claim reviewed promptly.

Our Team

TEAM MEMBERS

Florida Law Office Reviews

Slidell, Louisiana Law Office Reviews

Colorado Law Office Reviews

Metairie Law Office Reviews

Talk to a Plantation Business Interruption Lawyer Today

Godbey Giardina Law Group represents businesses throughout Plantation, Fort Lauderdale, Sunrise, and Broward County facing denied or underpaid business interruption claims. The sooner our attorneys review your policy and your documentation, the more options you typically have.

Contact us to schedule a free consultation and discuss your business interruption claim and legal options.

This webpage provides general information about business interruption insurance claims and does not constitute legal advice. Viewing this page or contacting Godbey Giardina Law Group does not create an attorney-client relationship. Trial results, verdicts, and settlements referenced on this site reflect our legal team's past experience; outcomes vary by case, and prior results do not guarantee a similar outcome in your matter. Florida insurance law, including Civil Remedy Notice and bad-faith requirements, is general and subject to change; confirm how it applies to your situation by contacting our office directly.

Don’t Wait Until It’s Too Late

Schedule your free consultation now and get the legal support you need to understand your Fire damage claim.